

Work with me: Private Investment Coaching

Using My Bank Screener
Last week’s post showcased my custom bank screener. This week I put it to use.
Here’s my search criteria:
Return on assets > 1.20%
Nonperforming loans < 1%
Net charge-offs (NCO) < 0.25%
Tangible equity/assets > 8%
Efficiency ratio < 65%
I took the resulting list of 440 banks and had Claude add price/tangible book (the screener can pick that up) and rank them based on P/TBV, 3-Yr ROE, and current return on tangible equity.
I then calculated a going-in return based on the current P/TBV and 3-Yr ROE. Here’s the top 10:
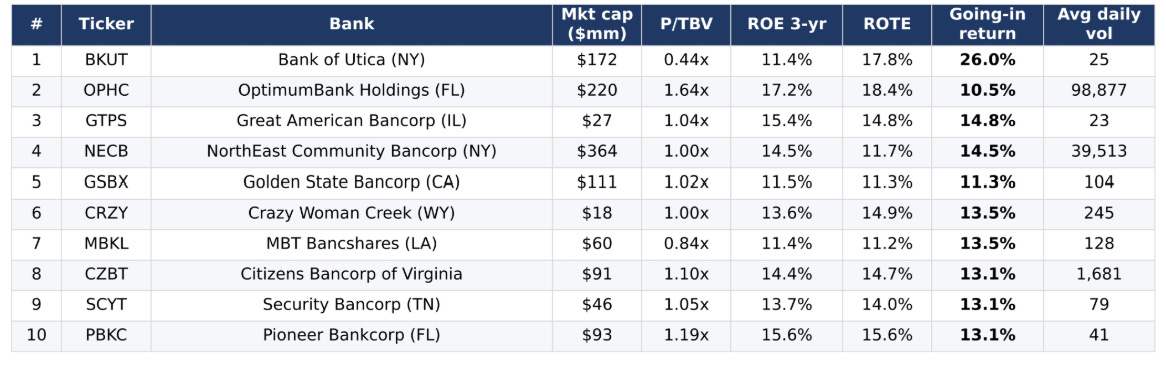
As you can see, these are thinly traded tiny banks, which means we’re probably in good hunting grounds. Two I’ve covered before: Crazy Woman Creek and Citizens Bancorp of Virginia.
Other than those two, here’s a first-pass screen of these names (i.e., you may know more than I do; please let me know if you have insights!).
Bank of Utica (BKUT | New York)
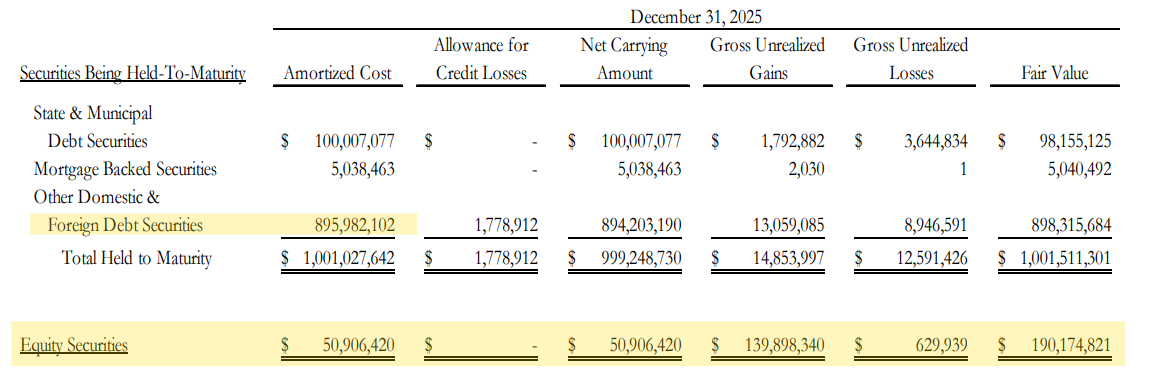
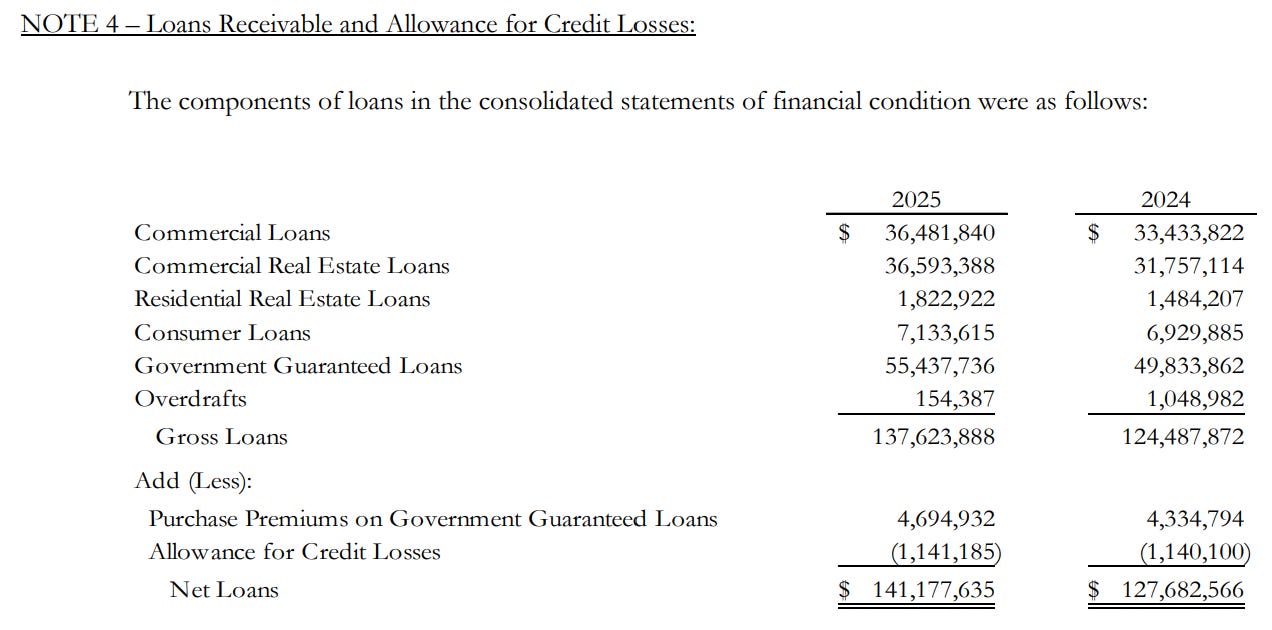
This looks like a very unusual bank. It’s effectively an investment portfolio with a bank charter. Two-thirds of its assets are in its HTM portfolio, with another ~13% in equities. Just 10% of assets are in loans. And it has a grand total of one branch.
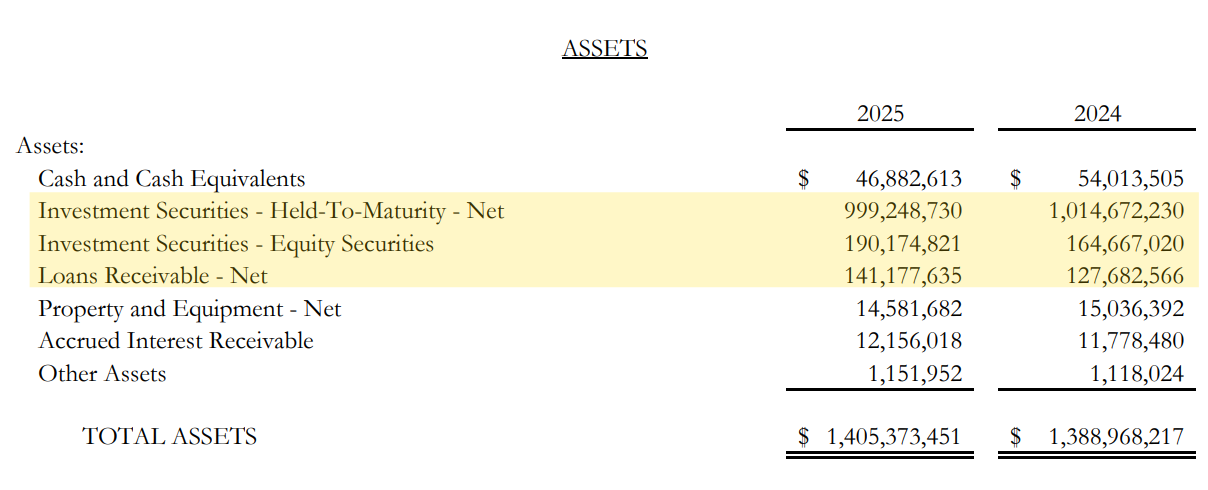
It appears that the spikes in ROA are due to the mark-to-market changes in the securities portfolio.
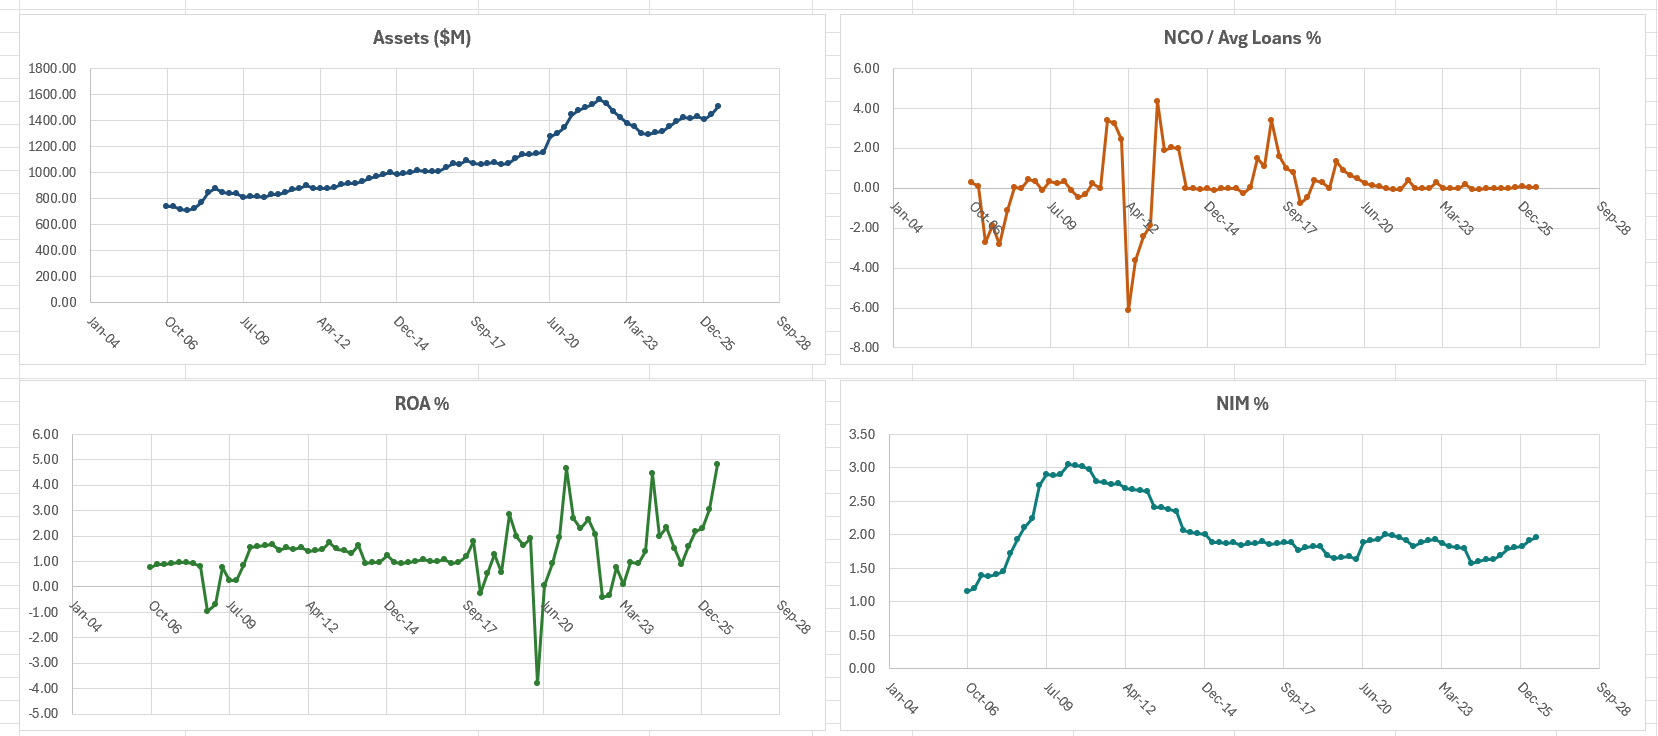
Digging into the securities portfolio, I’m even more curious. There’s nearly $900mm of foreign debt.
The relatively tiny loan book looks decent:
Caveat Emptor: I checked with a friend who knows BKUT. His advice: Stay away.
OptimumBank Holdings (OPHC | Florida)
Edit: My original market cap was wrong; corrected, P/TBV is 1.64x. I left it in as it seems to be a fairly well-run bank, just not as cheap as at first glance.
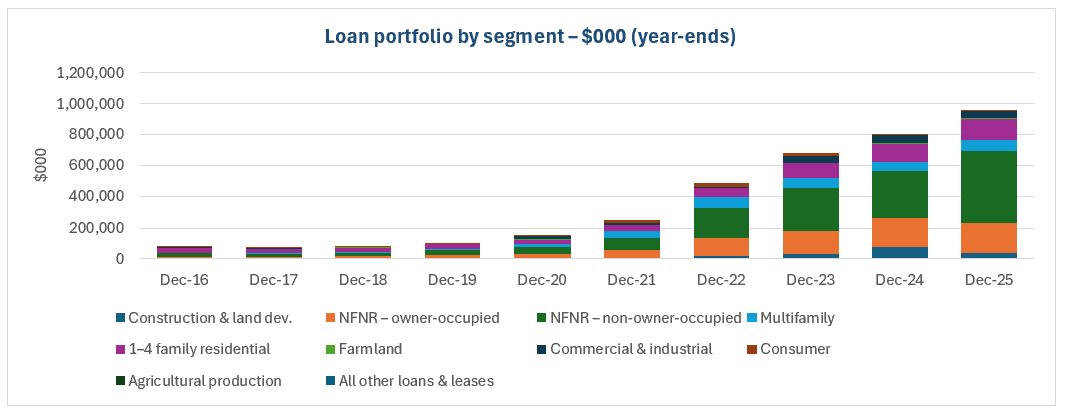
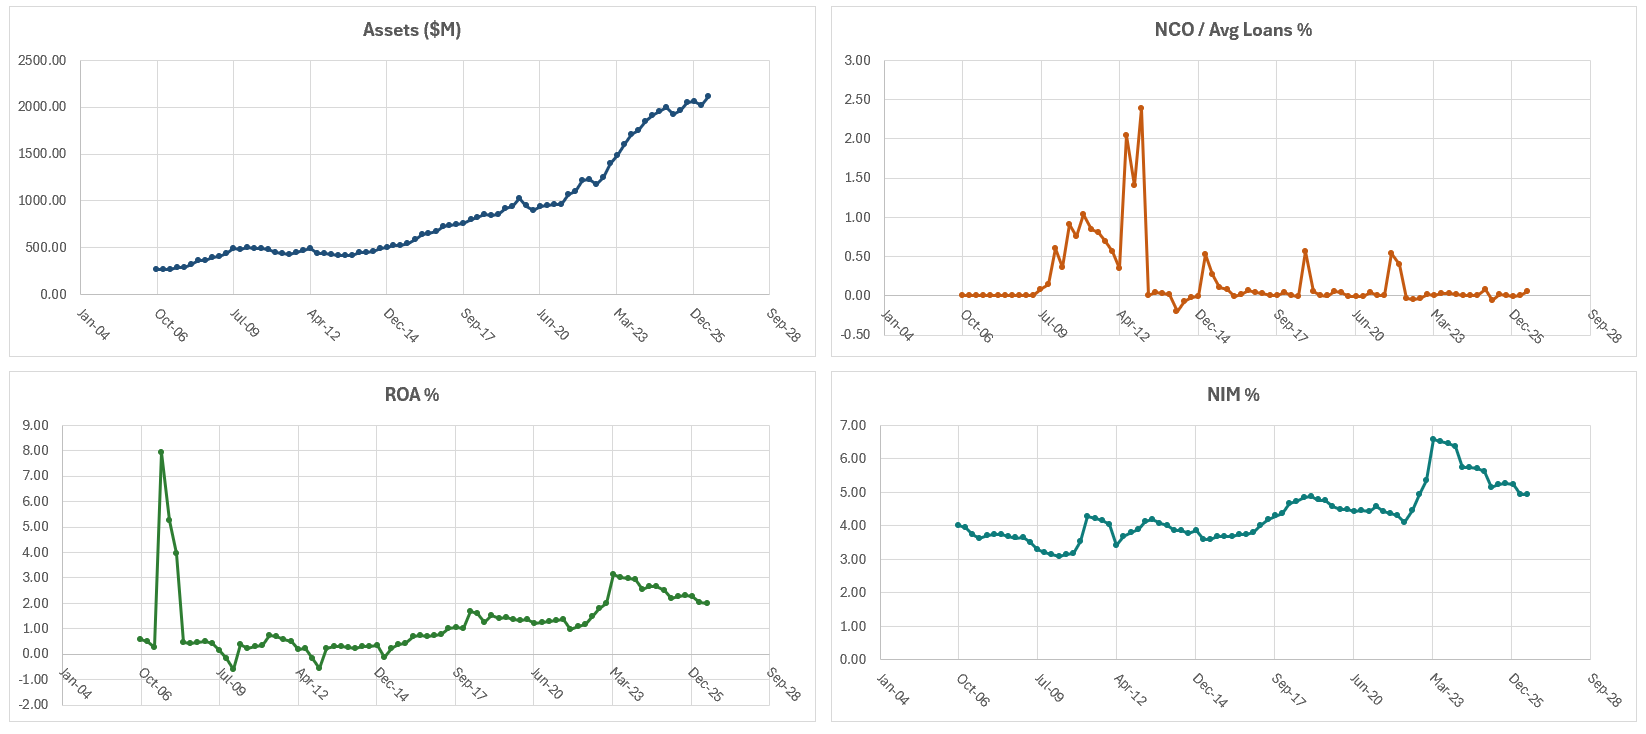
Optimum was a de novo in 2000 (when does it stop being de novo?) with 4 branches and a concentration in CRE (74% of loans).
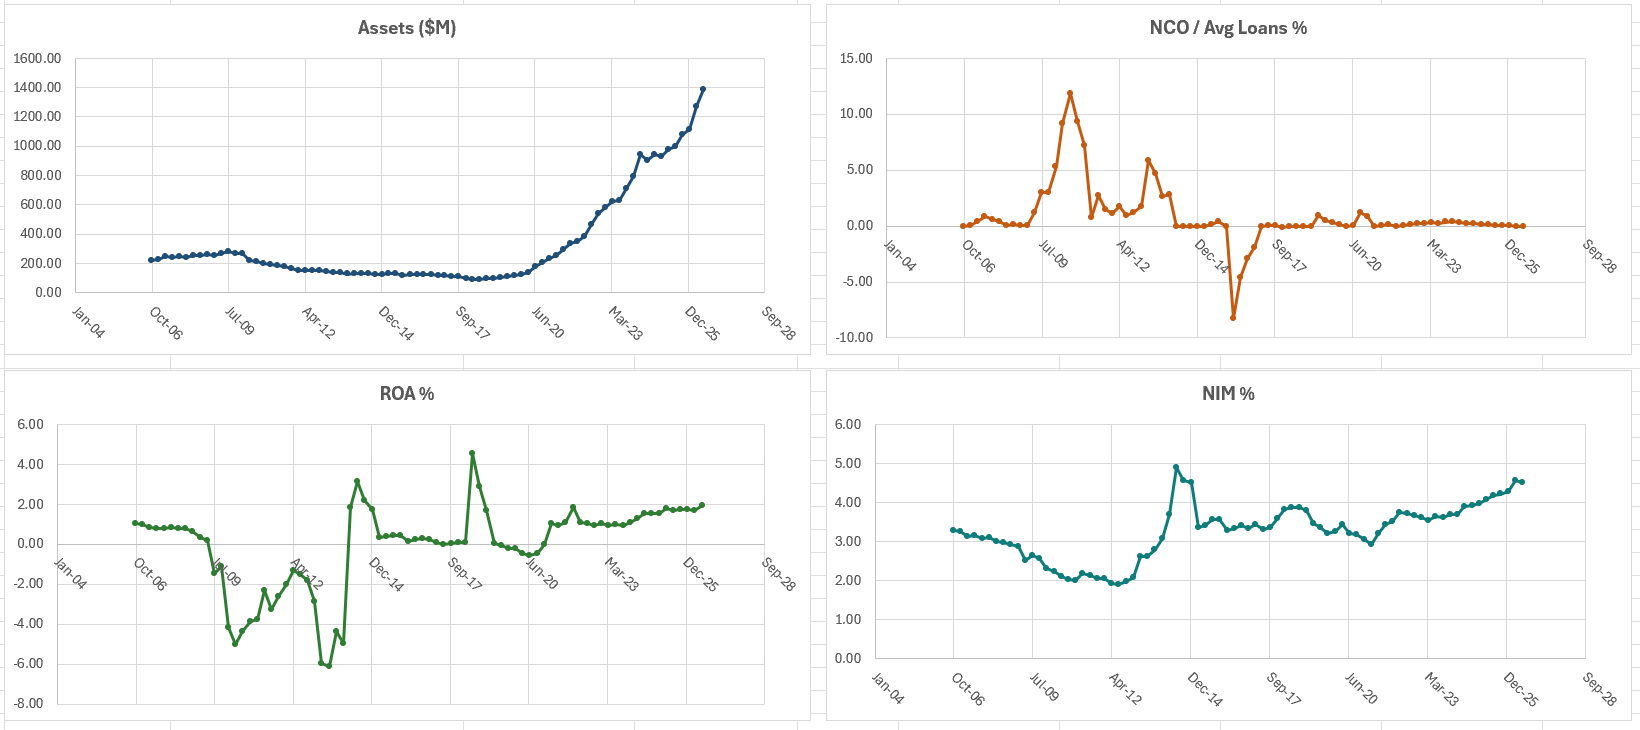
As the first chart illustrates, the bank spent 15 years at around $200mm in assets, then grew rapidly to $1.4 billion at the end of 2025. Doing a little more digging, it seems the bank raised capital multiple times between 2021 and 2025, a total of $58.8 million between common and preferred.
The bank has a niche in skilled nursing facilities, which are common in Florida. The bank’s two largest shareholders are directors who own SNFs, so there’s some expertise there.
Great American Bancorp (GTPS | Illinois)
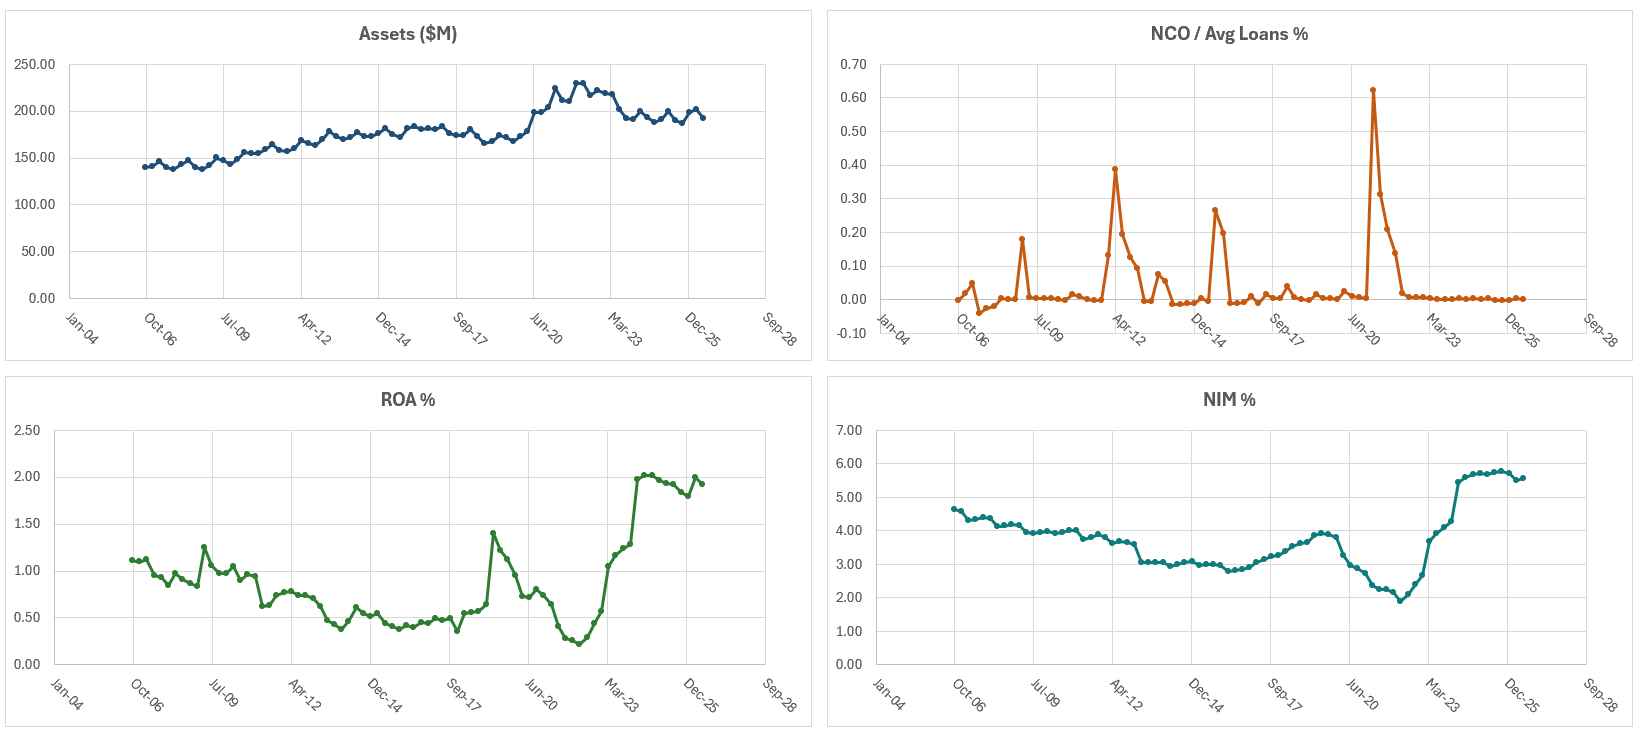
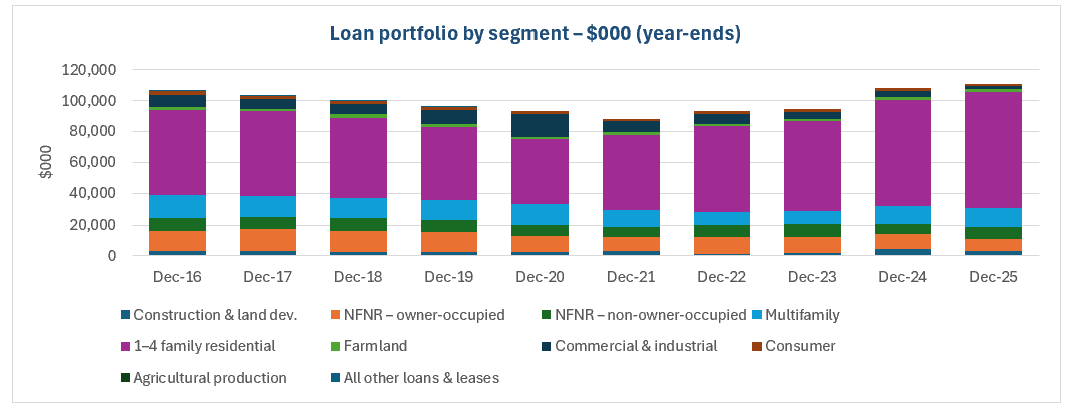
Great American is a 2-branch bank founded in 1908. It pairs a residential lending operation (68% of loans) with an insurance agency that boosts ROA.
The spikes in NCO look worrisome until you realize the chart is scaled to 70bps max.
Note: These charts are for First Federal Savings Bank of Champaign-Urbana, its bank sub.
NorthEast Community Bancorp (NECB | New York)
It trades at book value but has over 70% of loans in construction. Further, it’s 90% loaned up.
Looking deeper, NECB has its construction portfolio in 247 projects, primarily in residential construction (condo / townhome developments) north of NYC.
Golden State Bancorp (GSBX | California)
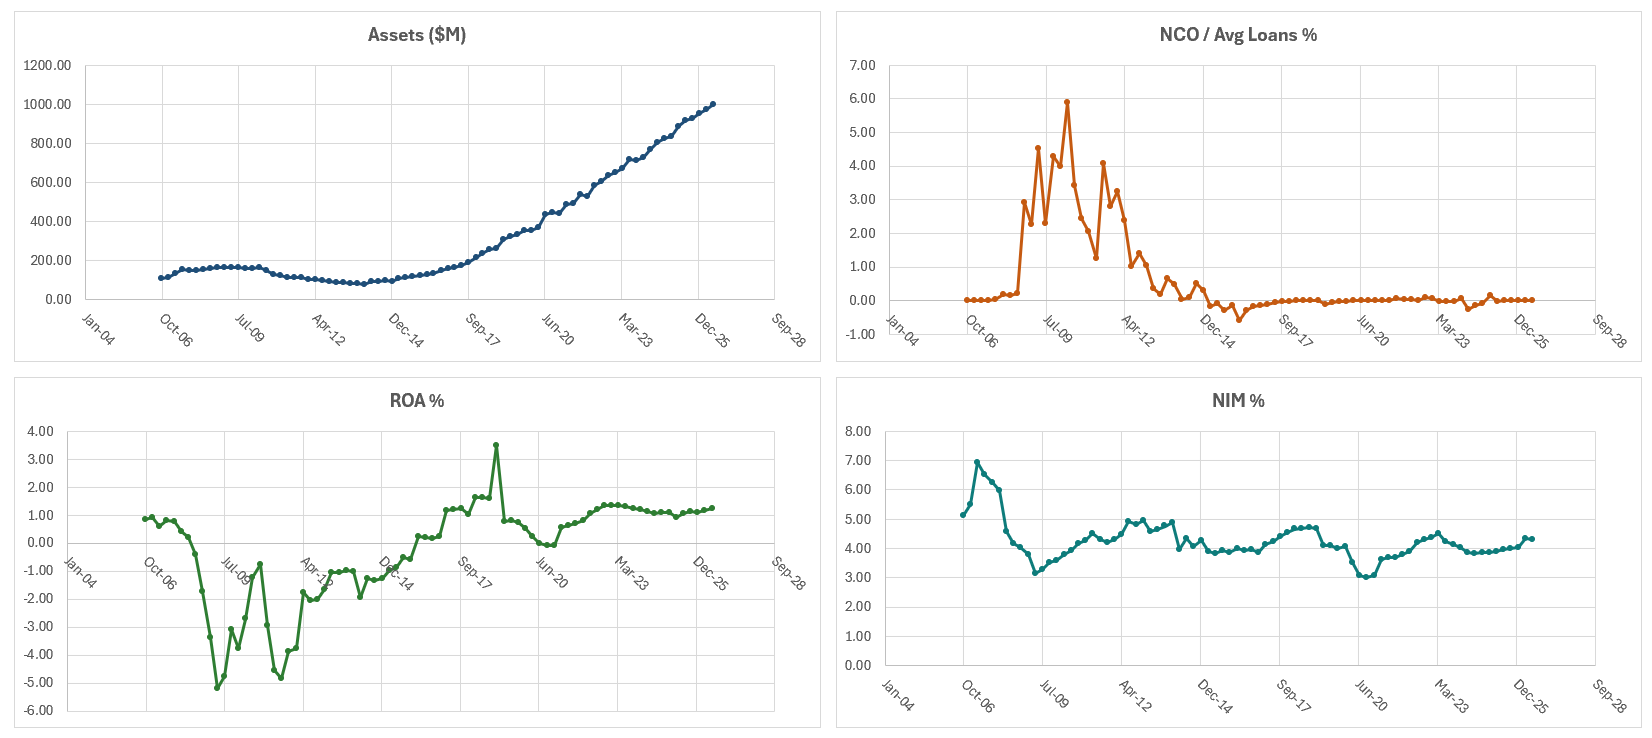
Here’s another de novo-ish bank founded in 2003. It has just $1 billion in assets across three branches, a $92mm market cap, and trades at 1.02x book.
The question I have is: will history repeat itself? It appears most of the board and management are new after the bank recapitalized in 2014-15, so the longer-term track record isn’t as deep of a black mark.
The Chairman and CEO owns 12% of the bank, and insiders in total own 32%; additionally, another 9% or so is owned by a fund run by a director.
Crazy Woman Creek Bancorp (CRZY | Wyoming)
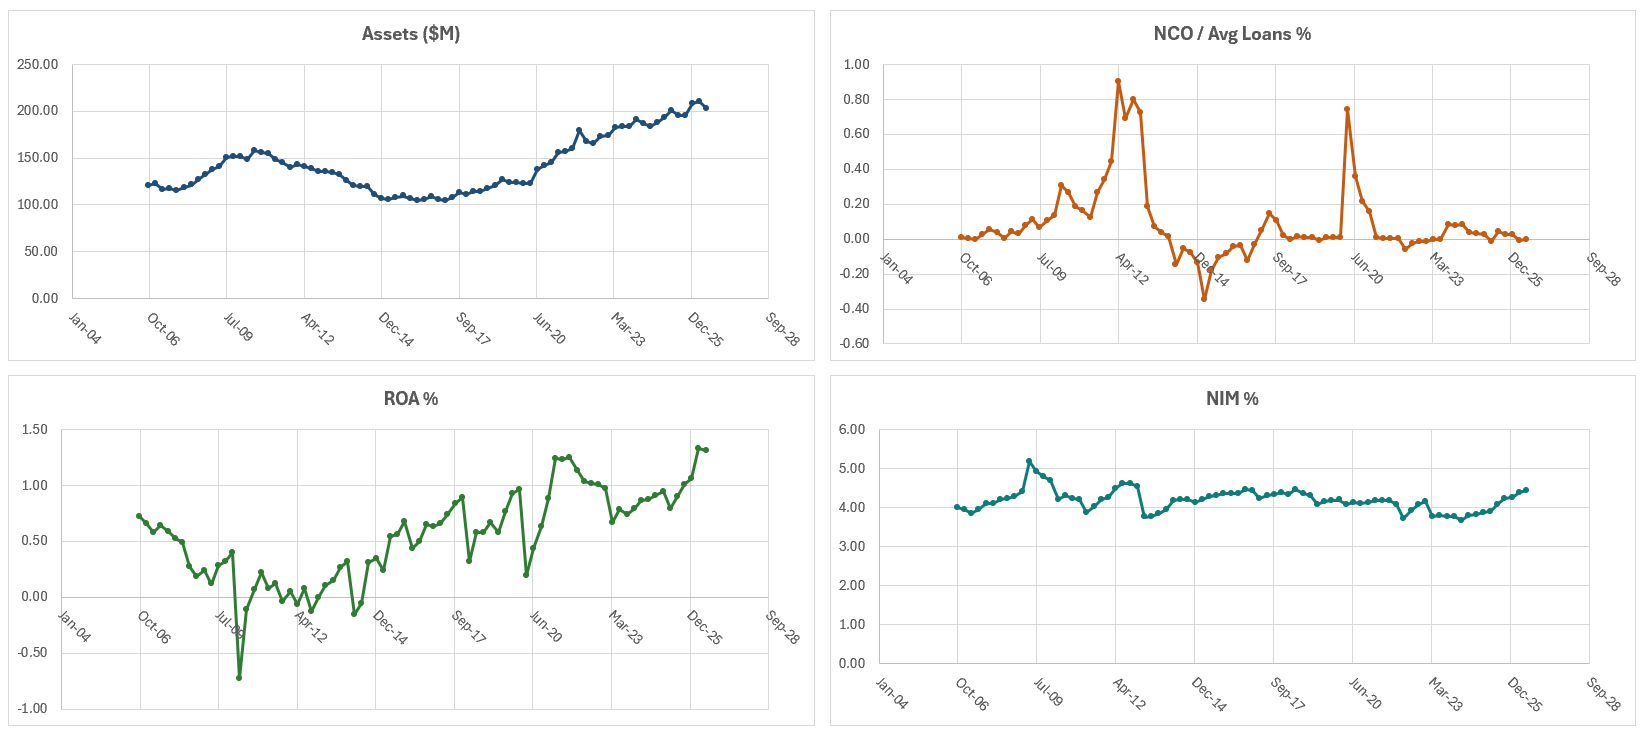
I covered this bank in February. It traded at 0.85x BV then and now trades at book.
This one proves that a relatively tiny bank can earn decent returns on assets. The only downside is it’s pretty opaque in terms of disclosure. I like it enough to keep it on my watchlist.
MBT Bancshares (MBKL | Louisiana)
This $650mm asset bank trades at 0.84x book. It has 8 branches around Metairie, LA. About half the loan book is in CRE and another third in residential.
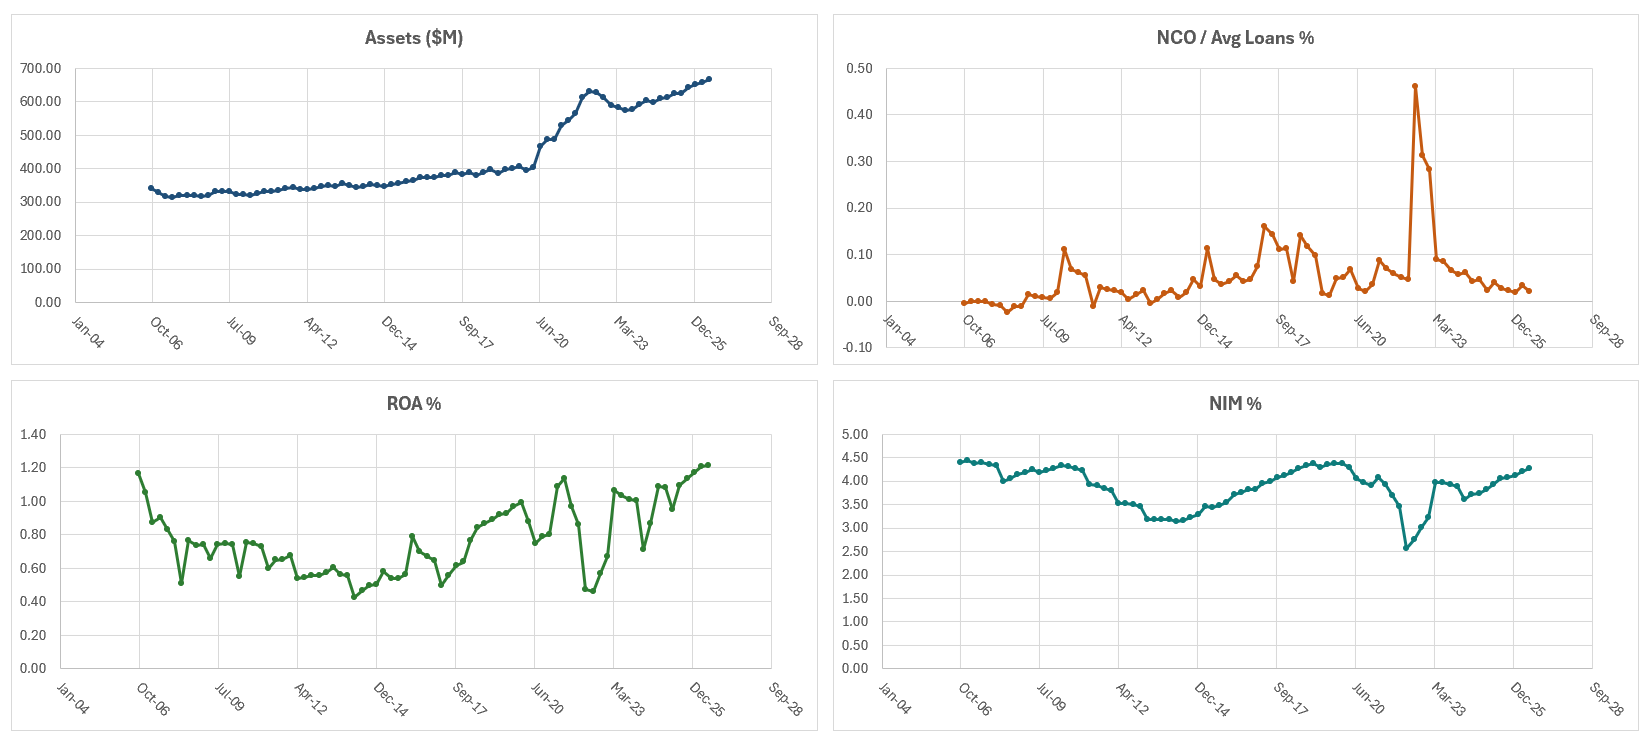
Note: At this point, I realized my screener annualized NCO data. So that 0.46% for MBT turned into 0.29%. I used the opportunity to revise the tool to use TTM figures.
Citizens Bancorp of Virginia (CZBT | Virginia)
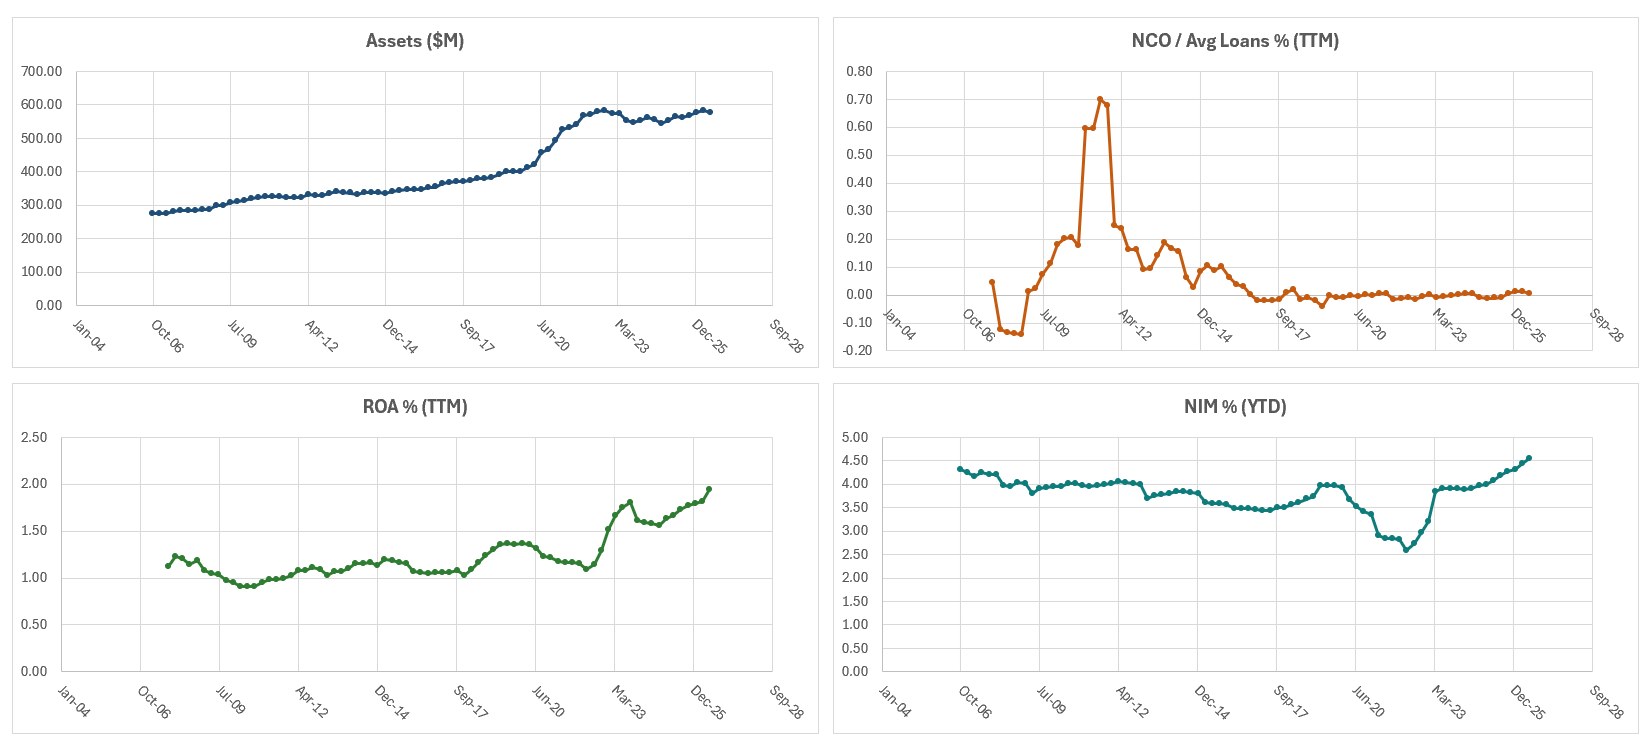
Here’s another one I covered in February. It’s since re-rated from 0.95x to 1.10x BV.
Given that track record of improving ROA, I think it probably deserves >1x BV. It appears to have a nice low-cost base of deposits, although noninterest-bearing deposits are only 23%.
Security Bancorp (SCYT | Tennessee)
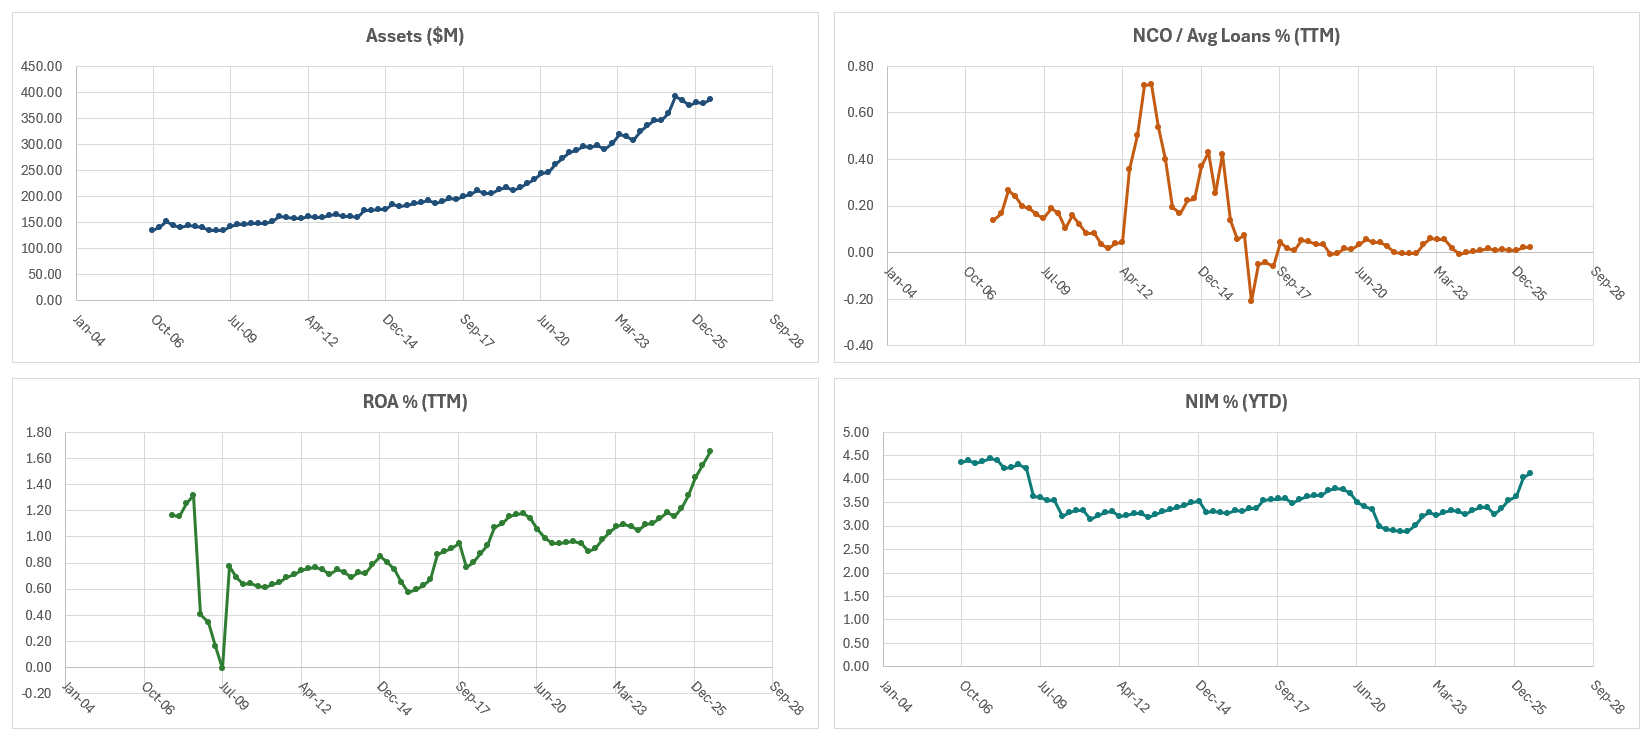
This $385mm asset bank has 3 offices in rural TN. It looks to be a slow grower and I like the steadily growing ROA. NCO in the early/mid-2010s were modest, and it appears to have had the same CEO since 2007.
Pioneer Bankcorp (PBKC | Florida)
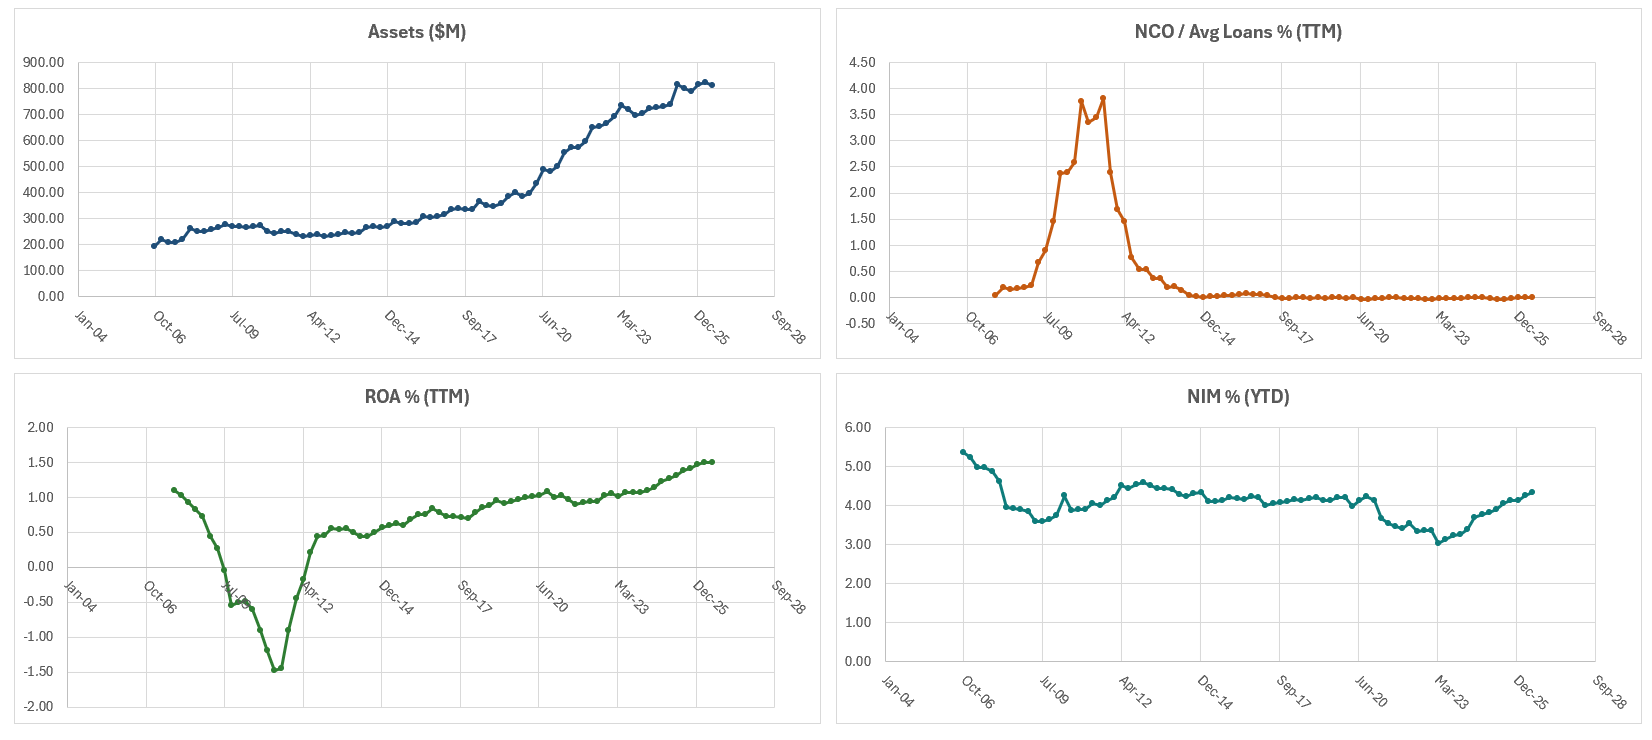
This 100-year-old bank has $800mm in assets across 7 branches and trades at 1.19x BV. It’s a bit pricier than the others but appears deserving of a higher valuation with ROA currently at 1.5% and climbing.
The stain on PBKC is the large losses in the GFC tied to Florida real estate. From 2009-11 the bank charged off 7.5% of the loan book. It looks like the holding company shareholders put in $5.5mm of fresh capital, and the bank suspended its dividend for 4 years.
More thoughts? Let me know in a private message or leave a comment.
Stay Rational!
Adam
Order the 2nd Edition Now!
Praise for the 2nd Edition
I’m incredibly grateful for the people who took the time to review early drafts of the new material and provided feedback, as well as praise for both editions:
“If you want to understand how Warren Buffett built Berkshire Hathaway into one of the most valuable businesses in the world, you have to read this book. This is your opportunity to stand beside Picasso as he paints each brush stroke. A must read for all Buffett and Berkshire groupies.”
— Bill Ackman, Founder and CEO of Pershing Square
“I and my teammates at the Gabelli Organization have been tracking Warren’s success for some 50 years. Adam’s book captures the work and highlights the history of Berkshire and the hard and diligent work of Buffett and Munger, Jain and Abel, and Combs and Weschler.”
— Mario Gabelli, Chairman and CEO, Gabelli Funds
“Adam Mead’s discussion of the values and virtues which have shaped Berkshire Hathaway over 50 years is a must read for those investors in search of the forces that have delivered such investment value over time.” — Thomas A. Russo, Gardner Russo & Quinn LLC
“Few activities can be more rewarding for any value investor than studying the history and evolution of Warren Buffett and Berkshire Hathaway. Adam has done us a huge favor with his yeoman efforts in producing this treatise. Since it is chronologically ordered, it is an invaluable reference guide for all things Berkshire.” — Mohnish Pabrai
“Adam continues to deliver a resource very valuable to both Berkshire fans and the investor community as a whole, his depth of knowledge is clearly demonstrated here again. I thoroughly enjoyed this latest addition.” — Dan Calkins, Chairman & CEO, Benjamin Moore
“The question must be asked, ‘Why another Berkshire book?’ When you read this monumental effort by Adam Mead, the answer will be obvious. Read cover to cover, both the uninitiated to Berkshire and its most ardent followers will derive enormous utility and satisfaction from it. I learned so many new and important things about Berkshire and its history. It is my pleasure to encourage you to enjoy this gem.”
— Christopher P. Bloomstran
“Whatever Adam writes is always first-class - guaranteed.”
— Andy Kilpatrick, Author, Of Permanent Value: The Story of Warren Buffett